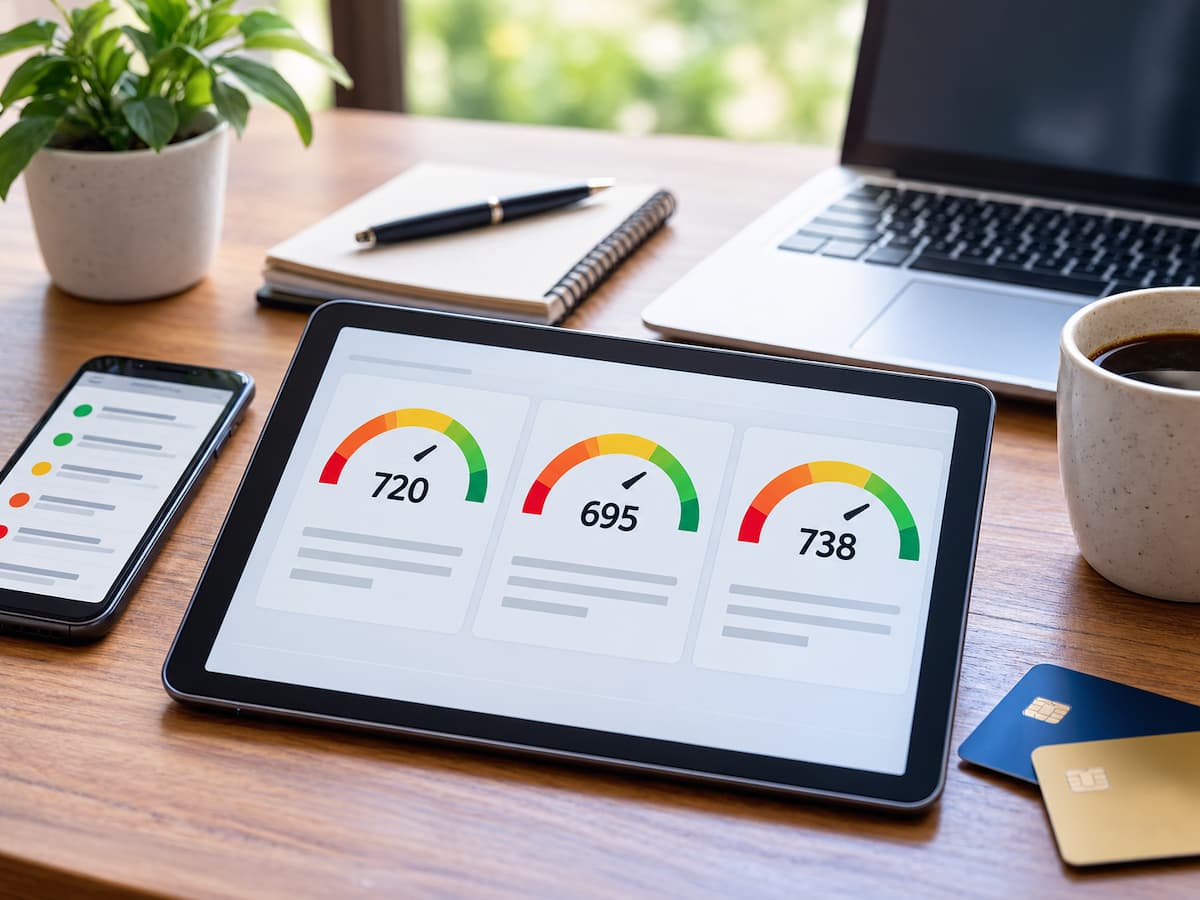
A credit score can look surprisingly different depending on which credit bureau or scoring model produced it. One report might show a score that is noticeably higher or lower than another, even though you are the same borrower.
That does not necessarily mean one bureau made a mistake. Credit bureaus can receive different information, update records at different times, and calculate scores using different scoring models. The result is that two legitimate credit scores can differ without either one being incorrect.
Understanding where those differences come from makes it easier to decide which score matters, what information to check, and when a discrepancy deserves attention.
Credit Bureaus Do Not Always Have Identical Information
Credit bureaus are separate companies that maintain credit files. Lenders and other participating businesses may report information to one, two, or several bureaus rather than necessarily sending identical data to every bureau.
For example, imagine you have three credit cards:
- Card A reports to all three major bureaus.
- Card B reports to only two.
- Card C has recently updated its balance with one bureau but has not yet appeared on another report.
The three credit files could therefore contain different balances, account histories, or even different accounts. This is one of the most important reasons credit scores can vary. A credit score is calculated from the information available in a particular credit report at a particular time. If the underlying reports differ, the resulting scores can differ too.
Different Update Dates Can Create Temporary Score Differences
Credit information does not necessarily reach every bureau simultaneously. Suppose you normally carry a $2,000 balance on a credit card with a $5,000 limit. You make a $1,500 payment before the lender reports your account information.
One bureau might receive the new $500 balance first, while another still shows the previous $2,000 balance. If the scoring model considers the higher balance, the second score could temporarily be lower. This is why checking two scores on different days can sometimes produce differences even when there has been no major change in your financial behaviour.
The reporting date can matter almost as much as the payment itself.
The Balance You See May Not Be Your Reported Balance
Your current credit card balance and the balance appearing on a credit report are not necessarily the same thing. A lender may report account information according to its own reporting schedule. Consequently, paying a balance today does not necessarily mean every credit report will immediately show a zero balance. For someone monitoring their credit before applying for a major loan, this timing difference can be particularly relevant.
Credit Scores May Use Different Scoring Models
Another major source of confusion is that there is no single universal credit-scoring formula. Different scoring models can evaluate the same credit report differently. For example, a lender or financial service might use one version of a FICO score, while another service provides a VantageScore. Even when both scores are calculated from similar underlying information, their algorithms and scoring criteria can differ.
That means comparing the numbers directly without checking the scoring model can be misleading. A 720 from one model is not necessarily equivalent to a 720 from another model in terms of how a particular lender will evaluate you.
Why This Matters More Than the Bureau Name
People often ask, “Which credit bureau has the correct score?”
That question can be too simplistic.
The bureau is only one part of the equation. You also need to know:
- Which credit report was used.
- Which scoring model was used.
- Which version of that model was used.
- When the information was last updated.
- What type of lender or financial decision the score is intended for.
Two different scores can both be valid because they answer slightly different scoring questions.
Your credit reports can contain different accounts.
Suppose you open a new credit card, and the card issuer reports the account to only some bureaus.
One credit report might now show:
- A new credit account
- A new credit limit
- A new account balance
- A recent inquiry
Another report might not contain the account yet.
The scoring difference may therefore have nothing to do with an error. The bureaus simply have different data. This can also happen with older accounts, closed accounts, personal information, and payment history. The key question is not simply whether your scores are different. It is whether the information used to calculate them is accurate.
Credit Utilisation Can Make Differences More Noticeable
Credit utilisation is another area where small reporting differences can have a meaningful effect. For revolving credit accounts such as credit cards, utilisation generally describes how much of your available credit is being used.
For example:
| Credit limit | Reported balance | Utilisation |
|---|---|---|
| $5,000 | $500 | 10% |
| $5,000 | $2,500 | 50% |
| $5,000 | $4,500 | 90% |
If one bureau receives a much higher reported balance than another, the resulting scores may differ.
This does not mean that carrying a particular balance is required to obtain a good score. It simply illustrates why the balance appearing on your credit reports can matter.
Payment History Differences Can Be More Serious
A small difference in a reported balance is one thing. A payment-history discrepancy deserves closer attention. Imagine one credit report correctly shows every payment as on time, while another incorrectly reports a late payment. That is not simply a normal difference between scoring models. It may indicate inaccurate information that should be investigated.
Look for differences involving:
- Missed or late payments
- Account status
- Current balances
- Credit limits
- Collection accounts
- Accounts that do not belong to you
- Dates an account was opened or closed
- Duplicate accounts
- Personal identifying information
If something is inaccurate, review the dispute process provided by the relevant credit bureau and the company that supplied the information.
Hard Enquiries Can Also Differ
When you apply for certain forms of credit, the lender may make a hard inquiry that can appear on your credit reports. Not every lender necessarily reports the inquiry to every bureau. As a result, one credit report might show an inquiry that another does not.
This is another reason why two otherwise similar credit files can produce different scores. It is useful to distinguish a hard inquiry from a soft inquiry. They are not interchangeable, and many common activities that involve checking credit do not have the same scoring implications as a hard credit application.
A Simple Example of Why Three Scores Can Differ
Consider a borrower whose three reports look like this:
| Factor | Bureau A | Bureau B | Bureau C |
|---|---|---|---|
| Credit-card balance | $1,000 | $1,000 | $2,500 |
| A new credit card was reported. | Yes. | Yes. | No |
| Recent inquiry | Yes. | No | Yes. |
| Payment history | On time | On time | On time |
The borrower has not behaved differently with each bureau.
The underlying data is simply different. Each scoring model receives its own version of the borrower’s credit information and produces a result based on that information. This is why seeing three different scores does not automatically indicate a problem.
When a Difference Is Normal—and When to Investigate
A difference between scores is often normal when the underlying reports contain legitimate differences or when different scoring models are being used.
You should investigate more carefully when the difference appears to be caused by incorrect information.
Usually Not a Reason for Alarm
A difference may be explainable if:
- One bureau has updated an account more recently.
- One report contains an account that another does not yet show.
- Different scoring models are being used.
- Reported balances differ because of reporting dates.
- One bureau received an inquiry that another did not.
Worth Investigating
Pay closer attention when:
- A late payment appears that you believe never happened.
- An account belongs to someone else.
- A balance or credit limit is clearly incorrect.
- The same debt appears incorrectly more than once.
- An account is shown as open when it should have been closed.
- Personal information is associated with an account you do not recognise.
The goal should not be to make every credit score identical. The goal is to make sure the underlying credit information is accurate.
Which Credit Score Should You Trust?
There is no universal “correct” score that applies to every situation. If you are preparing for a specific credit application, the most useful score may be the one based on the scoring model that the relevant lender actually uses.
A score displayed by a free credit-monitoring service can still be useful for tracking changes and spotting potential problems. However, it may not be the exact score a particular lender uses when making a credit decision.
This distinction is easy to overlook. Think of a credit score as a measurement produced for a particular purpose, rather than as a permanent personal number.
What to Do When Your Scores Are Far Apart
If the difference seems unusually large, don’t immediately assume that the lowest score is wrong.
Instead, compare the underlying reports.
1. Check the Scoring Model
Find out whether the scores use the same scoring system and version.
Comparing different models can make an otherwise explainable difference look more mysterious than it really is.
2. Compare the Reports Side by Side
Look specifically at:
- Account balances
- Credit limits
- Payment history
- New accounts
- Account closures
- Collections
- Hard enquiries
You are looking for the information that changed—not simply the score that changed.
3. Check the Reporting Dates
A report that was updated yesterday may contain information that another report will not receive until later.
Record the dates associated with major account updates when comparing reports.
4. Dispute Genuine Errors
If you identify inaccurate information, use the appropriate dispute process rather than attempting to “fix” the score itself.
The underlying information is what needs to be corrected.
5. Monitor the Result
After an error is corrected or a lender updates an account, allow enough time for the corrected information to be reflected in the relevant credit report and scoring model.
A score may not change immediately simply because an underlying issue was corrected.
Don’t Chase a Specific Number Without Knowing Why It Matters
Credit scores can become confusing when people treat the number itself as the objective. A better approach is to understand what is behind the number. If your scores are 710, 730, and 750, the difference may not require any action at all. If one score suddenly drops because a report incorrectly shows a missed payment, that is a different situation.
The useful question is therefore not:
“Why aren’t all my scores identical?”
It is:
“What information and scoring model produced each score, and is that information accurate?”
That question leads to a much more productive review.
FAQs
1. Why do I have different credit scores from different bureaus?
Credit scores can differ because credit bureaus may have different information, update information at different times, or provide scores calculated using different scoring models.
2. Which credit bureau has the most accurate score?
There is not necessarily one bureau with the universally “most accurate” score. Accuracy depends on whether the information in a particular report is correct and which scoring model is being used.
3. Can credit scores change even when I haven’t done anything?
Yes. A lender may report updated account information, such as a new balance or payment status, which can change a score even if you have not recently applied for credit or made another major financial decision.
4. Why are my credit scores different by 20 or 30 points?
A difference of that size can have several explanations, including different reported balances, account information, inquiries, reporting dates, or scoring models. Compare the underlying reports before assuming there is an error.
5. Should I dispute different credit scores?
You generally dispute inaccurate information on a credit report, not the fact that two legitimate scoring models produced different numbers. If the underlying report contains incorrect information, investigate the appropriate dispute process.
6. Will checking my own credit score lower it?
Checking your own credit information is generally different from applying for credit and having a lender perform a hard inquiry. However, the exact effect depends on what type of credit check is performed and how it is recorded.
The Bottom Line
Different credit scores do not automatically mean something is wrong with your credit. The most common explanations are differences in the information each bureau has, differences in reporting timing, and differences between scoring models. What matters most is whether the information in your credit reports is accurate and whether you understand which score is relevant to the financial decision you are considering.
If the numbers differ, compare the reports rather than focusing only on the scores. A legitimate difference may require no action at all; an inaccurate account, payment record, balance, or inquiry deserves investigation.

The Interest-Story Editorial Team creates practical financial guides covering budgeting, saving, debt, credit, side income, student finance, and everyday financial planning. Our content is written to make complicated financial topics easier to understand, with information organized around real-life questions and decisions. We use reliable sources for facts that can change over time and encourage readers to verify important financial, legal, and government requirements with the appropriate official organization. Our goal is straightforward: provide useful information that helps readers understand their options and make more informed financial decisions.